What Bankers Really Think
Bankers are a wealth of information.
Who else do you know that evaluates a variety of businesses every year (and sometimes monthly) that operate in different industries and geographies, and then make decisions whether to lend or invest?
Your accountants prepare the financial statements and tax returns for reporting to your banker and the tax people. It might be up to you to interpret the financial information. Your lawyer doesn’t evaluate your company; they prepare the important documents and agreements that will protect you and keep you out of trouble. Your banker has a wealth of valuable information that can help you grow your business.
Have you asked your banker for their advice lately?
Phil’s Profit Points™ in Brief:
Bankers evaluate your business based on numerous factors. The most important are management, a good plan, and cash flow.
Bankers are aligned with your interests because they want you to be successful and grow your business.
Most bankers probably know more about your numbers than you do.
Interest rates are at historical lows and provide a strong incentive to borrow wisely in order to grow your business and maximize your wealth.
Recently, I interviewed twelve senior bankers for a banker survey that I was conducting to determine banking trends and best practices that my clients needed to be aware of to increase their borrowing leverage and success.
Figure 102.1 What The Bankers Wants
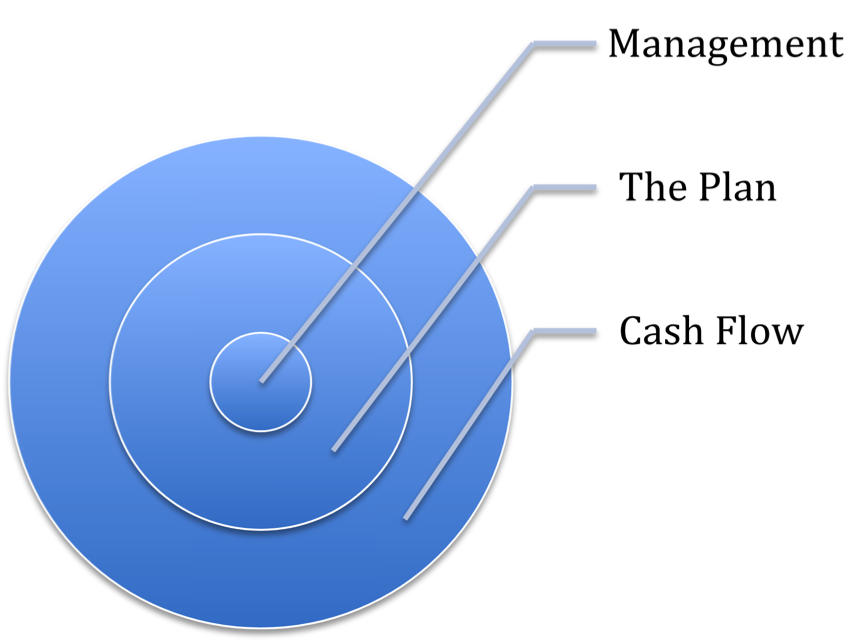
Here is wise advice from bankers.
Management
“I advise entrepreneurs to ask their banker to challenge them on their ideas. Why will this plan be successful, or not, and what are the opportunities, risks, and value they are providing to their customers,” advises Doug Yaremko with HSBC.
Tip: use your banker as a sounding board.
“Our best clients see us as a strategic partner, nurture the relationship, and have open communication with us about their plans, future needs and goals,” states Tafaline Wall, with Bank of Montreal.
Tip: use your banker as a strategic partner to help you plan.
“Small business owners don’t reach out enough to ask for help from professionals. The people that make the most money are more inclined to ask for help and advice,” according to Lon Sokalski of Edmonton.
Tip: ask your professionals for proactive advice about the future.
“It’s easier to evaluate a financing request when the owner involves his or her Chief Financial Officer, because it’s more about the business and the numbers than just the owner’s plan,” recommends Daryl Marcia, formerly with Royal Bank of Canada, and now a wealth advisor with RBC Dominion Securities.
Tip: take a professional approach that is based on objective numbers to evaluate your business.
“There are good times and bad times in every business and in every industry. In every case, good management can mitigate these risks,” recommends Ian Thoms with TD Bank.
The Plan
“The best managers don’t just use their business plan to obtain financing. They use the plan to run their business,” states Doug Yaremko, Associate Vice President with HSBC.
Tip: use your business plan to run your business and hold your people accountable.
“The number one reason for declining a loan application is a lack of planning,” says Peter Scrivener with National Australia Bank.
Tip: Develop a formal plan, complete with goals, alternatives, risks and recommendations, that will help you achieve success.
“Being unprepared for growth can break a company,” cautions Kevin Anderson with Roynat Capital.
Tip: Be prepared for success and have financing in place for high growth.
“Our best clients come with a well prepared plan and all of the required information. If it takes someone a long time to generate important information, that decreases our confidence,” says Chad Haidey from CIBC.
Cash Flow
“Positive historical cash flow is absolutely critical to support a lending request. And, don’t buy a major asset using working capital. Match the asset with financing,” asserts Kevin Anderson with Roynat Capital.
Tips: Measure your total days to cash monthly. Measure your net cash flow weekly. Balance your working capital with CapEx (capital expenditure) financing and plans.
“Businesses that are in growth mode need to be careful about aggressive tax strategies that legitimately reduce net income and taxes but also reduce retained earnings and the company’s ability to borrow to fund future growth,” advises Chris Windjack from the Business Development Bank of Canada.
Tip: Focus on growth, first, and tax, second, to drive your business. Don’t let tax drive the bus.
All the bankers agree that the owner needs to be prepared to inject cash into the business to strengthen the company’s balance sheet, overcome slow periods, and come up with down payments that can facilitate more borrowing.
Tip: be prepared to be your own banker, or at least to fund the down payment for expansion or additional financing.
In Conclusion
You can access great advice from your banker, for free. Just ask them.
Tough Question
Would you lend to your business?
**From the Vault **
A strong banking relationship can help you to fund exponential business growth and dramatically increase your wealth.


